






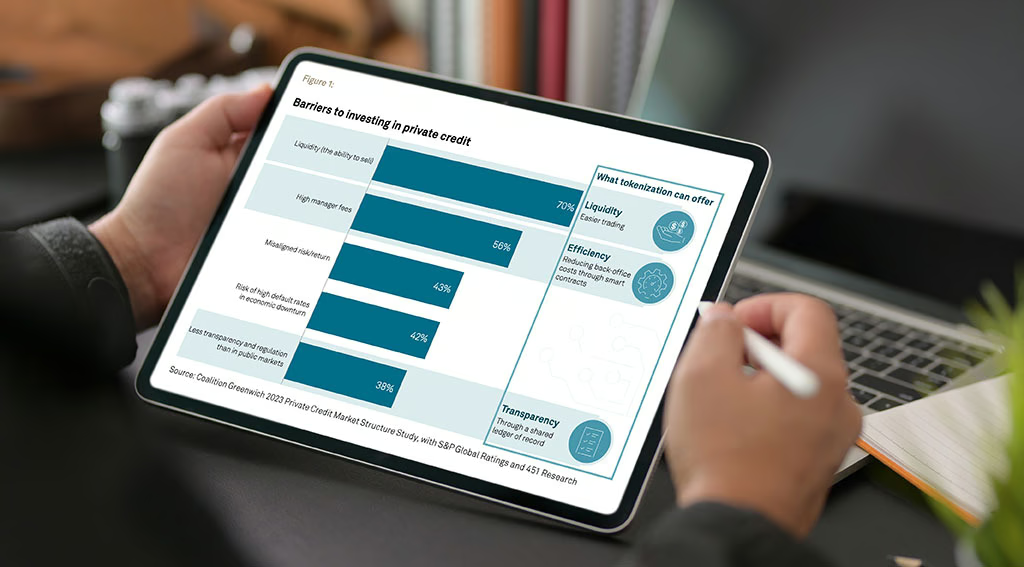
The tokenized private credit sector is rapidly evolving, offering new ways for investors to access yields derived from real-world and onchain credit. Despite being grouped under a single label, these products vary widely in structure, risk, and yield sources. Some provide direct exposure to loans, while others act as wrapper tokens representing offchain credit, structured funds, or programmable DeFi products. The common thread is the tokenization of credit flows to make them more accessible and transparent.
Tokenized private credit converts traditional private loans and debt into blockchain-based digital tokens, making them more liquid, accessible, and automated. It is designed for institutional investors, financial institutions, and smaller investors who want exposure to private credit with lower barriers and faster processes.
Key benefits include increased liquidity and fractional ownership, operational efficiency through automation, real-time transparency, and integration with DeFi for additional yield. However, credit risk, regulatory uncertainty, and immature secondary markets remain important considerations.
— Zeus (@ZeusRWA) March 27, 2026
Real-world assets meet blockchain
Platforms like Maple Finance and Centrifuge are bridging traditional finance and crypto. They leverage capital pooling to offer loans, where repayment creates on-chain yield. Centrifuge, on the other hand, allows blockchain investors to gain exposure to real-world credit, such as invoices or structured loan books.
Even though blockchain provides transparency, underlying issues like default risk, enforceability, and servicing quality persist. These platforms demonstrate that blockchain is a secondary layer of transparency and accessibility for tokenized real-world private credit.
Yield in crypto and interaction with DeFi
There are also platforms that are focused on improving liquidity and programmability. Platforms such as Securitize and STOKR are distribution layers that offer traditional private credit in a more accessible format. Hastra is a yield conversion platform that converts real-world loan yields, such as HELOC, to a format that is compatible with DeFi.
Pareto Finance offers a full lifecycle approach with products such as USP and sUSP. These products allow multiple loans to be combined under a single programmable structure. OnRe also points out the variety of “credit” with reinsurance exposure. This is where the returns are generated based on underwriting rather than lending
At the same time, European Central Bank Executive Board member Piero Cipollone has emphasized that as the ecosystem of stablecoins and tokenized deposits grows, achieving true stability will require a trusted public anchor in central bank money, stronger legal frameworks, and effective public-private cooperation.
Why investors are still interested in 2026
Despite those challenges, tokenized private credit continues to attract attention because it addresses several weaknesses in traditional private markets.
Blockchain infrastructure can automate parts of issuance, reporting and settlement. It can also allow lenders and investors in different jurisdictions to interact through a common digital system, subject to the relevant regulatory requirements.
For institutions, that could mean faster settlement and better visibility into portfolios. For borrowers, on-chain lending could eventually create another source of capital outside banks and traditional private-credit funds.
Enjoyed this? Bookmark DeFi Planet, explore related topics, and follow us on Twitter, LinkedIn, Facebook, Instagram, Threads, and CoinMarketCap Community for seamless access to high-quality industry insights
Take control of your crypto portfolio with DEFI PLANET PRO, DeFi Planet’s suite of analytics tools.